
Ada, MI · Kent County
A Financial Advisor in Ada Who Actually Works for You
You're doing well in Ada. But the house, the raise, the bonus and a 401(k) you've barely looked at are all decisions that compound for decades, and you're making them by feel. We build a real plan around your life and make sure it gets done.
You're Doing Well in Ada, but Wonder If You're Making the Right Moves
A lot of people put down roots in Ada: a bigger house, a school district they picked on purpose, a commute that works. The income usually is not the problem. The problem is that the big decisions land all at once, and nobody is looking at how they fit together.
How much goes toward the house and how much toward retirement? What should this year's bonus actually do? Is the stock or deferred pay at work a good deal, or something you'll regret not understanding? Most people answer these one at a time, from a search result, and hope it adds up.
It rarely adds up on its own. Small mistakes are easy to make, and the longer they go unaddressed, the more expensive they get to fix.

Before vs. After Villaire Financial
Without a Plan
- Looking at homes in Ada without knowing how much house still leaves room to save
- Opening a property tax bill that came in higher than the seller's
- A bonus or raise that quietly disappears into everyday spending
- Stock, equity or deferred pay at work that you don't fully understand
- A 401(k) contribution set years ago and never revisited
- Googling your way through major decisions and hoping you got it right
With Villaire Financial
- Know how much home you can afford and still fund retirement
- An estimate of your new bill before you make an offer
- A plan for every raise and bonus, decided in advance
- Your benefits explained and put to work in the plan
- Contributions and accounts matched to your tax picture
- Never wonder if you made the right call
Is This Built for You?
We work best with people who have a lot going on financially and want someone in their corner to get everything working together.
Early-Career Professionals
Making good money and close to the biggest purchase of your life. Right accounts, right order, right house. We make sure you're not guessing.
Growing Families
A bigger home, a school district, a 529, life insurance and a mortgage all at once. We put them on one timeline so none of them gets starved.
High Earners at Large Employers
A strong income, a benefits package with more moving parts than anyone explained, and a nagging feeling you should be further along. That gap is what we close.
What clients say about working with Chris
"My wife and I have been working with Chris for a few years now. He's been absolutely incredible with helping us manage our finances."
"Chris is one of the most genuine people you will meet in the financial services industry. I trust him to do what is right and he is considerate with all his clients."
"Since getting married two years ago, he has helped us create clear financial plans, stay on top of our money, and set up funds that actually make us feel confident about our future."
Testimonials from current clients of Villaire Financial, LLC. No compensation was provided for these reviews. Individual experiences and results will vary. These testimonials may not be representative of the experience of other clients.
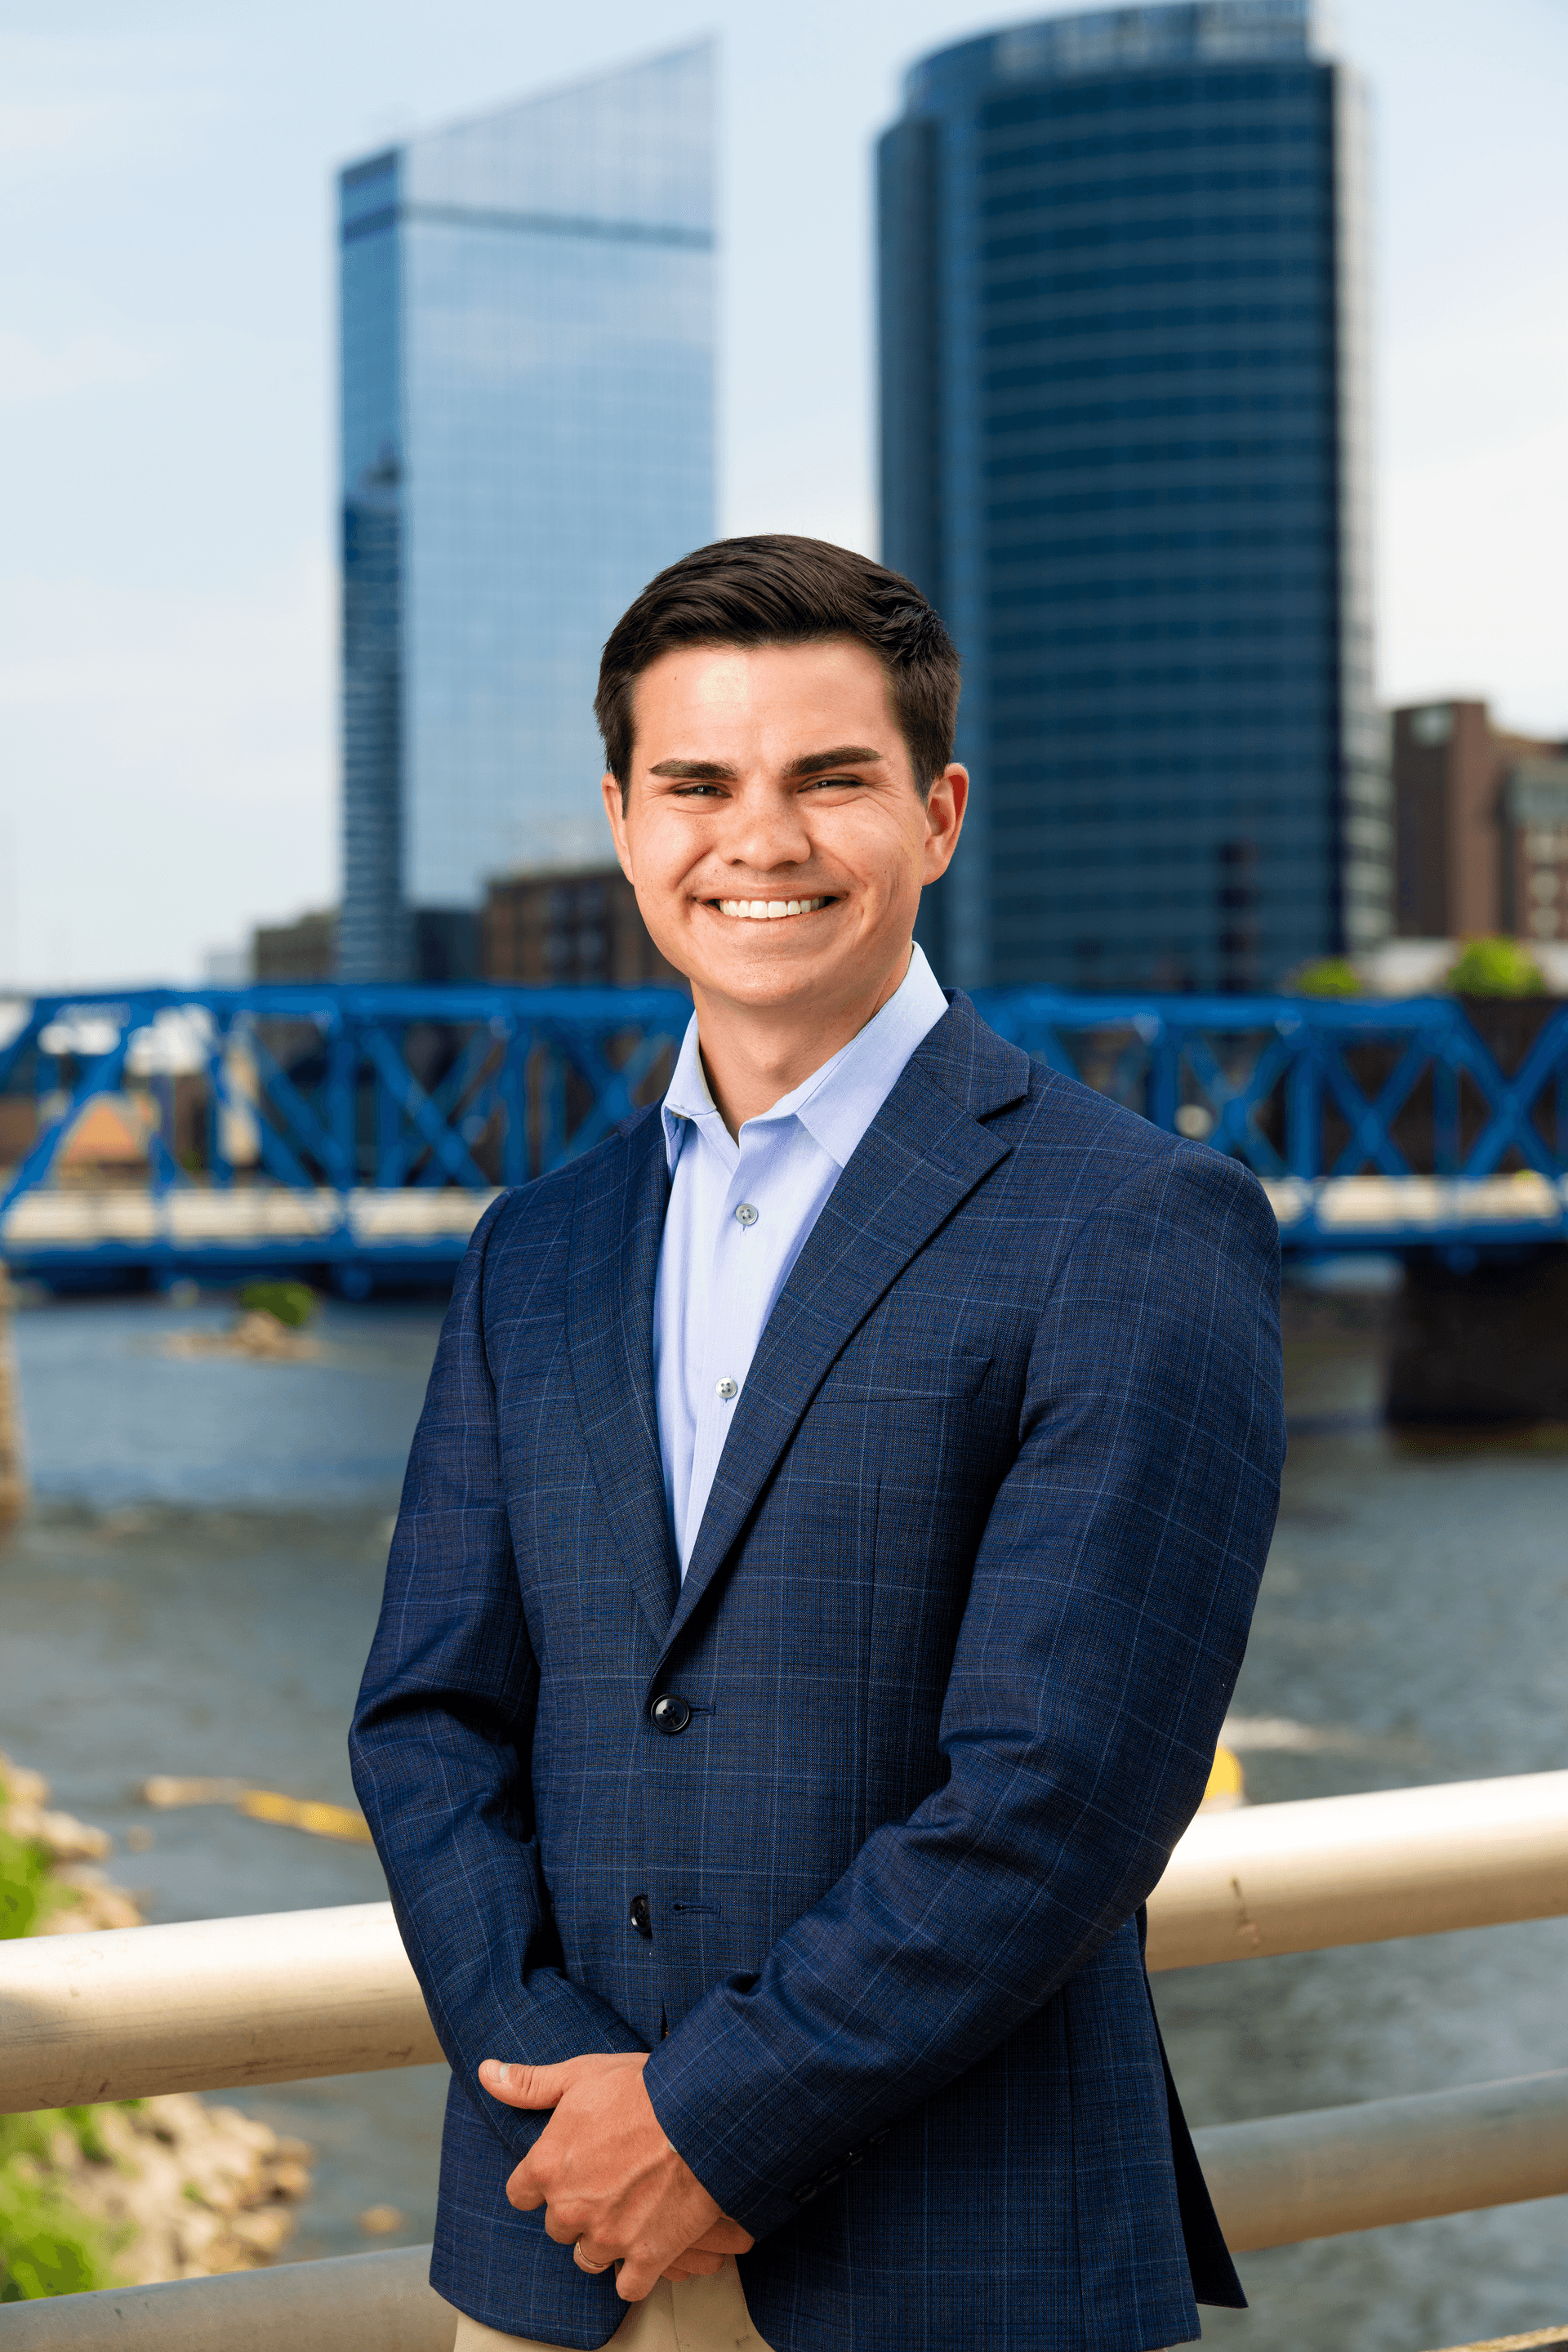
A financial advisor near Ada who makes sure you're actually building the life you want.
Villaire Financial is a fee-only, fiduciary planning firm led by Chris Villaire, CFP®. The office is in downtown Grand Rapids, about 15 minutes from Ada, and most meetings are by video. Planning starts at $50 a month after a $250 onboarding fee, with no asset minimum and no commissions.
Chris started Villaire Financial because the financial services industry has largely overlooked people in their 20s and 30s for decades. He built this firm for young professionals who want clarity and direction with their money, and he is in the same stage of life as his clients.
Meet ChrisYour full financial plan in 30 days. Then we're there as life goes on.
- 1
Week 1
Book a Free 30-Minute Intro Call
Schedule a 30-minute call directly on our calendar. We'll hear about your situation, answer your questions, and tell you honestly if we think working together makes sense.
- 2
Week 2
Deep-Dive Discovery Session
Once we've decided to move forward, we schedule a deeper meeting covering income, expenses, investments, debts, insurance, taxes, and what you're actually trying to accomplish.
- 3
Weeks 3-4
Your Financial Plan
We build your plan across every area of your finances, then meet to present it and walk through it together so you understand the reasoning behind every decision. From there, we handle the execution: account setup, money movement, and your personalized client portal.
- 4
Onward
Ongoing Reviews and Support
We meet at least twice a year to review progress and adjust as life changes. Between meetings, you can reach out whenever something comes up.
What you walk away with
- A personalized financial plan covering every area of your financial life
- A clear picture of where you stand and what to do next
- A secure client portal with all your accounts and goals in one place
- Ongoing investment management, handled for you
- Twice-yearly reviews and an advisor you can reach between meetings
Working with Chris from Ada
Our office is downtown at 2 Fulton St W, Suite 122, but you never have to come in. Everything can be done by video and digitally, from meetings to signing documents to your client portal. If you'd rather meet in person, we're about 15 minutes from Ada. Meetings are by appointment only, and parking is validated in the garage attached to the building.
2 Fulton St W, Suite 122
Grand Rapids, MI 49503
Mon to Fri, 9 to 5 · (586) 322-2953
What it costs. No surprises.
Fee-only means you pay Chris and no one else pays him. Every fee is in writing before you commit to anything.
| One-time onboarding | $250 |
|---|---|
| Planning, per month | $50 to $125, based on income and complexity |
| With $100,000+ managed | Monthly fee waived |
| Investment management | 1.00% to 1.50% a year, only if Chris manages your investments |
| Asset minimum | None |
| Commissions | None |
What People in Ada Usually Ask First
Do I have to come to Grand Rapids to work with Chris?
No. Everything can be done by video and digitally, from meetings to signing documents to the client portal. If you would rather meet in person, the downtown Grand Rapids office is about 15 minutes from Ada, by appointment only, with parking validated in the garage attached to the building.
How much does a financial advisor cost in Ada, MI?
The one-time onboarding fee is $250. Ongoing planning is $50 to $125 a month depending on income and complexity, and it is waived once you have $100,000 or more in managed assets. If Chris manages your investments, that is 1.00% to 1.50% a year on the assets he manages, and the rate drops as assets grow. There are no commissions and no asset minimum.
Is there a minimum amount I need to work with Villaire Financial?
No. There is no asset minimum, and the firm was built for people who are still building wealth rather than sitting on it.
Can I buy a home in Ada and keep saving for retirement?
Often yes, but it depends on the price, the down payment, and what you are already saving. The median Ada Township home is valued at about $544,700, according to the Census Bureau's latest five-year estimate, so 10% down is roughly $54,470. The common mistake is pulling that cash out of savings and cutting 401(k) contributions to fund the purchase, which can leave you with a house and a thin retirement account. We put the down payment, the monthly cost, your retirement contributions and your emergency fund on one timeline, so you know what you can comfortably spend, which is often less than what a lender will approve.
What happens to property taxes when I buy a home in Ada Township?
A home's taxable value resets to the State Equalized Value, which is 50% of market value, the year after a sale. The seller may have been paying on a number that grew slowly for years, so your bill can come in well above theirs. If it will be your primary residence, file a Principal Residence Exemption affidavit with the township assessor to remove up to 18 mills of school operating tax. We estimate the new bill before you make an offer so it is in your budget from day one, and the Ada Township assessor can give you the current rates.
Does Ada, MI have a city income tax?
No. Ada is a township, and in this part of Michigan only Grand Rapids and Walker charge a city income tax. If you work in Grand Rapids you owe the nonresident rate of 0.75% on wages earned there, which is $900 a year on a $120,000 salary, and if you work in Walker the nonresident rate is 0.5%. If you work from home some days, the city has its own rules for those days, so check with the Grand Rapids Income Tax Help Center at (616) 456-3415 or your tax preparer. We build the tax into your cash flow either way.
I work for a large employer. What should I bring to the first meeting?
Your benefits summary. Ada is home to Amway's world headquarters and plenty of people here work for large employers, and the first thing Chris asks for is the 401(k) match, any equity or stock purchase plan, deferred pay, and your health plan and HSA options. Those documents decide a lot of what your plan looks like.
Is Villaire Financial a fiduciary?
Yes. Villaire Financial is a fee-only registered investment adviser, so it is legally required to act in your best interest and it is paid only by its clients, never by commissions or product sales.
One Conversation. No Commitment.
A free 30-minute call. You'll leave with a clear answer on your biggest financial priority and an honest read on whether working together makes sense.
Not ready to talk yet?
The Path to Financial Freedom
A free 17-page walkthrough of budgeting, debt paydown, investing, and tax strategy, written for people in their 20s and 30s who want a clear starting point.
Download the Free GuideWorth Reading Next
Practical advice for busy professionals, with clear next steps you can actually use.
Buying Your First Home in Grand Rapids: A Complete Financial Checklist
West Michigan's housing market moves fast. A complete financial checklist for buying your first home in Grand Rapids, before you start shopping.
How to Allocate a Bonus or Raise Without Lifestyle Creep
A raise feels like progress, but lifestyle creep quietly cancels it out. How to allocate a bonus or raise so your extra income actually builds wealth.
Financial Planning for High Earners Who Feel Behind
You earn good money but don't feel financially secure. Here's why that gap exists and what it actually takes to close it.
Other areas we serve
Sources
- Census Reporter, Ada township, Kent County (ACS 2024 5-year)
- Michigan Treasury, Principal Residence Exemption
- City of Grand Rapids, Income Tax Department
- Forest Hills Public Schools, attendance area map
- Google Maps, driving directions to the office
Census figures are 2024 five-year American Community Survey estimates and carry a margin of error. Tax rates and program rules change, so confirm current figures with the city, the township assessor or a tax professional. Examples are for illustration only. This page is general information, not tax, legal or investment advice. Last reviewed September 21, 2026.