Ann Arbor, MI · Serving All of Michigan
A Financial Advisor Serving Ann Arbor, Entirely by Video
Ann Arbor is full of residents, researchers, engineers and new grads who never left, all early in big careers. The pay is climbing, and so is the rent. The benefits are generous but complicated. We build a real financial plan around all of it and meet with you by video.
Great at Your Job, Still Guessing With Your Money
Plenty of people in Ann Arbor are a few years out of school with a real salary for the first time, a lease that renews every year, and a benefits portal full of choices nobody walked them through.
Do you take the retirement match right away, and when does it start? Should student loans be paid down or kept for forgiveness? Is it time to buy, or is renting smarter in a city this expensive? Each question touches the others.
Get the order wrong and you can leave a match on the table or pay off a loan that would have been forgiven. Those mistakes are easy to make in your first few years and expensive to undo later.
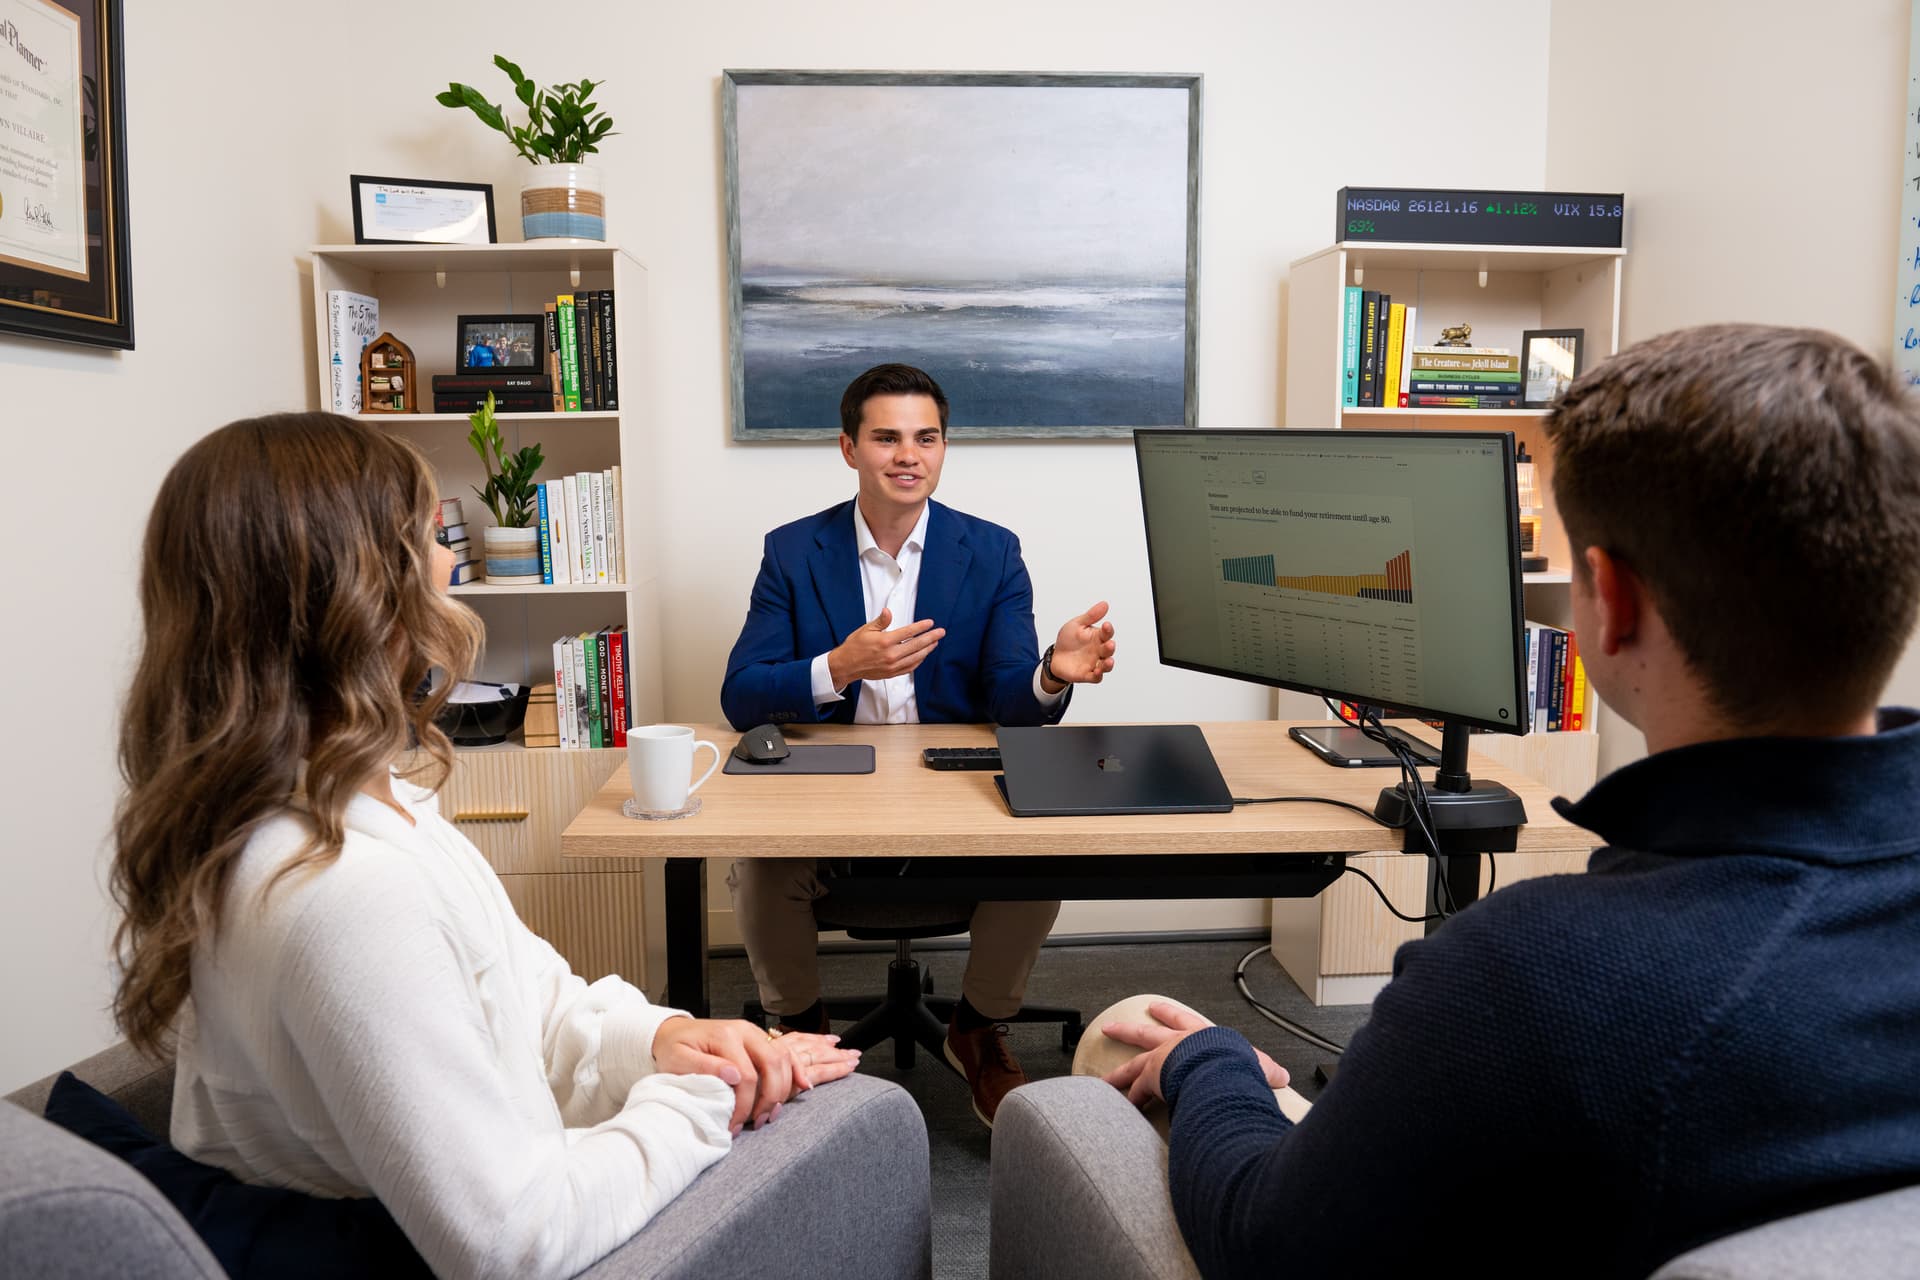
Before vs. After Villaire Financial
Without a Plan
- A benefits portal full of plans you never compared
- Paying extra on student loans without knowing if forgiveness applies
- Rent going up each year and no plan for a down payment
- Finishing residency or grad school with no plan for the first real paycheck
- Googling your way through major decisions and hoping you got it right
With Villaire Financial
- Every account chosen on purpose, with the match captured first
- A loan strategy built around where you work and how long you plan to stay
- A buy-or-keep-renting answer with a timeline and a savings target
- A first-year plan for the new salary, written before the raise disappears
- Someone to check big decisions with before you make them
Is This Built for You?
We work best with people who have a lot going on financially and want someone in their corner to get everything working together.
University and Hospital Employees
Generous retirement plans with rules that take a while to learn. We make sure you use them well from your first year.
Residents and Recent Grads
A real salary, real student loans and very little free time. We handle the planning so you can focus on the work.
Renters Thinking About Buying
In a high-cost market the math is tighter. We show you when buying makes sense for you, and when it does not yet.
What clients say about working with us
"My wife and I have been working with Chris for a few years now. He's been absolutely incredible with helping us manage our finances."
"Chris is one of the most genuine people you will meet in the financial services industry. I trust him to do what is right and he is considerate with all his clients."
"Since getting married two years ago, he has helped us create clear financial plans, stay on top of our money, and set up funds that actually make us feel confident about our future."
5.0 average Google rating as of October 14, 2026, based on 74 reviews posted to the Villaire Financial, LLC Google Business Profile since the firm opened in 2022. Google is not affiliated with Villaire Financial. No compensation was provided for any review. Ratings may not represent every client's experience and are not a guarantee of future results.
Testimonials from current clients of Villaire Financial, LLC. No compensation was provided for these reviews. Individual experiences and results will vary. These testimonials may not be representative of the experience of other clients.
A financial advisor for Ann Arbor who makes sure you're actually building the life you want.
Villaire Financial is a fee-only, fiduciary financial advisor in Grand Rapids that works with young professionals in Ann Arbor by video. Led by Chris Villaire, CFP®, we plan around University of Michigan benefits, student loans and the rent-or-buy question. Planning starts at $50 a month after a $250 onboarding fee, with no asset minimum.
Chris started Villaire Financial because the financial services industry has largely overlooked people in their 20s and 30s for decades. He built this firm for young professionals who want clarity and direction with their money, and he is in the same stage of life as his clients.
Meet ChrisYour full financial plan in 30 days. Then we're there as life goes on.
Week 1
Book a Free 30-Minute Intro Call
Schedule a 30-minute call directly on our calendar. We'll hear about your situation, answer your questions, and tell you honestly if we think working together makes sense.
Week 2
Deep-Dive Onboarding Meeting
Once we've decided to move forward, we schedule a deeper meeting covering income, expenses, investments, debts, insurance, taxes, and what you're actually trying to accomplish.
Weeks 3-4
Your Financial Plan
We build your plan across every area of your finances, then meet to present it and walk through it together so you understand the reasoning behind every decision. From there, we handle the execution: account setup, money movement, and your personalized client portal.
Onward
Ongoing Reviews and Support
We meet at least twice a year to review progress and adjust as life changes. Between meetings, you can reach out whenever something comes up.
What you walk away with
- A personalized financial plan covering every area of your financial life
- A clear picture of where you stand and what to do next
- A secure client portal with all your accounts and goals in one place
- Ongoing investment management, handled for you
- Twice-yearly reviews and an advisor you can reach between meetings
Working with us from Ann Arbor
Meetings happen by video and get scheduled around your shifts or your lab hours. Documents are signed online, and the plan and your accounts live in one client portal.
The office is in downtown Grand Rapids. You never need to visit, but you are welcome to if you are ever on that side of the state.
Meetings are by video, documents are signed online, and your plan lives in a client portal you can open from anywhere in Michigan.
Book a free intro callWhat it costs. No surprises.
Fee-only means you pay us and no one else does. Every fee is in writing before you commit to anything.
| One-time onboarding | $250 |
|---|---|
| Planning, per month | $50 to $125, based on income and complexity |
| With $100,000+ managed | Monthly fee waived |
| Investment management | 1.25% a year (lower above $500,000), only if we manage your investments |
| Asset minimum | None |
| Commissions | None |
What People in Ann Arbor Usually Ask First
I work at the University of Michigan. How does the retirement match work?
U-M's Basic Retirement Plan is a two-for-one match. You contribute 5% of salary and the university adds 10% once you have a year of service and are enrolled, and the plan vests immediately, according to U-M's 2026 enrollment guide. The 403(b) SRA and the 457(b) let you save more, with no match. We decide how much goes into each based on your loans, your taxes and how long you expect to stay.
Will I have to join the U-M retirement plan?
Eventually, if you stay. U-M's Standard Practice Guide requires regular employees who are 35 or older, have two or more years of service and hold a 100% appointment to participate. Most people come out ahead by joining long before that, since the university's 10% starts after the first year. If cash feels tight, we find the 5% in your budget instead of skipping the match.
Can my student loans be forgiven if I work at the university or the hospital?
Possibly, through Public Service Loan Forgiveness. Government employers, including public universities, qualify, and PSLF forgives the remaining federal Direct Loan balance after 120 qualifying monthly payments made while you work full time for a qualifying employer. If forgiveness is likely, extra payments can cost you money, so we settle the strategy before you send another one.
Is it better to rent or buy in Ann Arbor?
It depends on how long you will stay. The Census Bureau's latest five-year estimate puts the median Ann Arbor home at about $453,400, so 10% down is roughly $45,340, and median rent at about $1,649 a month. Fewer than half of occupied homes in the city are owned by the people living in them. If you might leave after residency or a postdoc, renting and investing the difference often wins. If you are staying, we build a down payment timeline and check whether a MSHDA MI 10K loan could help.
Does Ann Arbor have a city income tax?
No. Ann Arbor is not on the Michigan Treasury's list of cities that levy an income tax, so your income is taxed only at the federal and state level. If you take a job in Detroit, Lansing or East Lansing, those cities do tax nonresidents who work there, so it is worth checking before you accept an offer. Detroit's nonresident rate, for example, is 1.2%.
How do I know an Ann Arbor financial advisor is working in my best interest?
Ask whether they are fee-only and whether they will put their fiduciary duty in writing. A fee-only advisor is paid only by clients, never by commissions, which removes the reason to sell you a product. Villaire Financial is a fee-only registered investment adviser and our founder, Chris Villaire, is a CFP® professional, so both answers are yes, and you can confirm his certification on the CFP Board's website.
How much does a financial advisor cost in Ann Arbor, MI?
The one-time onboarding fee is $250. Ongoing planning is $50 to $125 a month depending on income and complexity, and it is waived once you have $100,000 or more in managed assets. If we manage your investments, that is 1.25% a year on the assets we manage, and the rate drops above $500,000. There are no commissions and no asset minimum.
Is there a minimum amount I need to work with Villaire Financial?
No. There is no asset minimum, so you can start before you have built up much in savings.
Is Villaire Financial a fiduciary?
Yes. Villaire Financial is a fee-only registered investment adviser, legally required to act in your best interest and paid only by its clients, never by commissions or product sales.
One Conversation. No Commitment.
A free 30-minute call. You'll leave with a clear answer on your biggest financial priority and an honest read on whether working together makes sense.
Not ready to talk yet?
The Path to Financial Freedom
A free 17-page walkthrough of budgeting, debt paydown, investing, and tax strategy, written for people in their 20s and 30s who want a clear starting point.
Download the Free GuideWorth Reading Next
Practical advice for busy professionals, with clear next steps you can actually use.
How Public Service Loan Forgiveness (PSLF) Works, and When to Actually Use It
PSLF can wipe out your federal student loans after 10 years. Here's how it works, who qualifies, and when forgiveness beats paying them off yourself.
Managing Money in Grad School and Residency Before a Big Income Jump
You're on a trainee income now, but a big raise is coming. Here's how to budget, handle loans, and set up your money before the jump.
Before You Pay Off Student Loans, Do This First
Before you throw extra money at student loans, there's a step most people skip. This guide explains exactly what to do before aggressively paying them down.
Other areas we serve
Sources
- Census Reporter, Ann Arbor city (ACS 2024 5-year)
- University of Michigan, 2026 Retirement Savings Plans enrollment guide
- University of Michigan HR, Retirement Savings Plans
- University of Michigan Standard Practice Guide 203.05, Retirement Savings Plan
- Federal Student Aid, Public Service Loan Forgiveness
- Michigan Treasury, Which cities impose an income tax?
- Michigan Treasury, 2025 City of Detroit individual income tax forms and instructions
- MSHDA, MI 10K DPA Loan
Census figures are 2024 five-year American Community Survey estimates and carry a margin of error. Tax rates and program rules change, so confirm current figures with the city, the township assessor or a tax professional. Examples are for illustration only. This page is general information, not tax, legal or investment advice. Last reviewed October 15, 2026.